Last updated: 26 August 2026
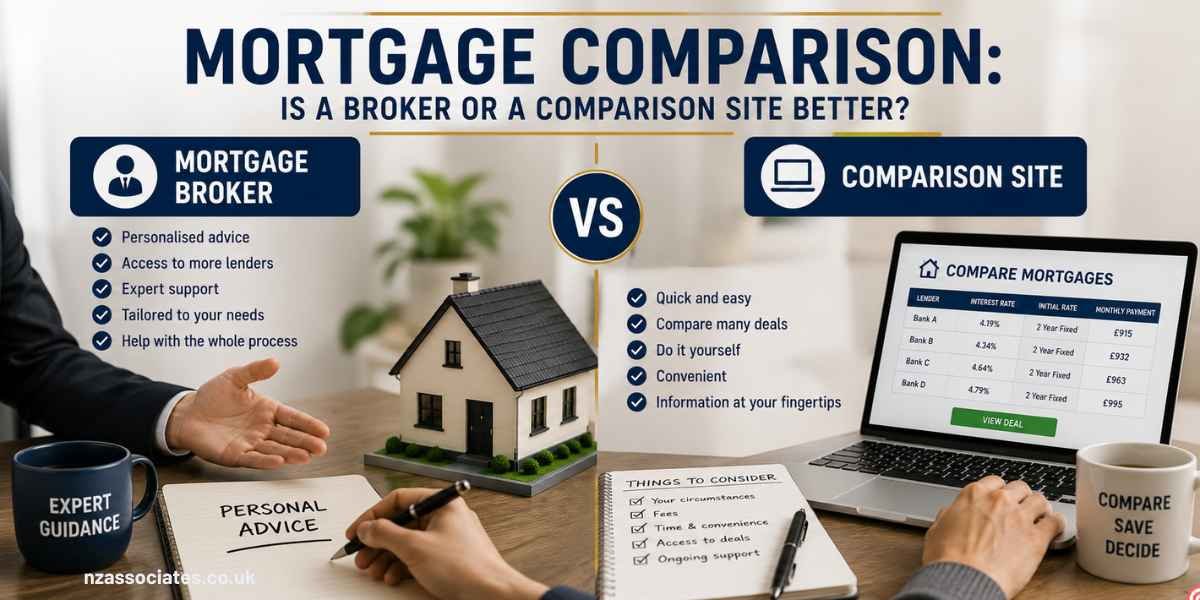
The short answer is a broker, for the vast majority of buyers. Mortgage comparison sites like MoneySuperMarket, Compare the Market and Uswitch show you headline rates from their partner lenders, but they cannot tell you which rate you actually qualify for. A whole-of-market mortgage broker assesses your full circumstances, including deposit source, credit history, employment type and property details, then matches you to a lender likely to say yes at the best available rate, including deals that never appear on comparison sites at all.
This distinction matters more than it sounds. A comparison site works from limited information: property value, deposit, and loan type. It cannot see whether you are self-employed with one year of accounts, whether your deposit is gifted, or whether you have a historic CCJ. A broker asks all of these questions before recommending anything, which is why the rate a broker finds is often different, and frequently better, than the headline figure a comparison site displays.
This guide walks through exactly how each option works, where comparison sites genuinely help, where they fall short, and how to use both together to get the best outcome.
Speak to an FCA-regulated whole-of-market broker, free and no obligation →
What’s on this page
- How do mortgage comparison sites work? ⇊
- How does a mortgage broker work differently? ⇊
- Broker vs comparison site: side by side ⇊
- Where comparison sites genuinely help ⇊
- Where comparison sites fall short ⇊
- Do brokers really access deals comparison sites don’t show? ⇊
- How to use both together ⇊
- How UK Mortgage Finder can help ⇊
- Frequently asked questions ⇊
How Do Mortgage Comparison Sites Work?
Mortgage comparison sites pull headline rate data from a panel of partner lenders and display it based on a handful of inputs you provide, typically property value, deposit amount, and mortgage type. Sites like MoneySuperMarket, Compare the Market, Uswitch and GoCompare earn commission when you click through to a lender or partner broker, which is how the service stays free to use.
The rate shown is usually the lender’s best advertised rate for someone who fits their standard criteria exactly. It is not a personalised quote. Comparison sites are useful for getting a rough sense of where the market sits, current rate ranges by LTV band, and which lenders are actively competing on price. What they cannot do is confirm you will actually be offered that rate once a lender assesses your full application.
Most comparison sites now route you to a broker partner (MoneySuperMarket and Uswitch both partner with Mojo Mortgages, for example) once you want a personalised recommendation, which is a tacit admission that the comparison table alone is not enough to complete a mortgage application.
How Does a Mortgage Broker Work Differently?
A whole-of-market mortgage broker starts with a detailed fact-find rather than a rate table. Before recommending anything, a broker will ask about your income type and stability, deposit source, credit history, existing debts, the property type, and your future plans (are you likely to move or remortgage within the fixed period?). This information determines which lenders will actually approve your application, not just which lender advertises the lowest rate.
Brokers search products from over 90 lenders, including specialist lenders like Kensington, Aldermore and Precise Mortgages that do not appear on consumer comparison sites at all, because these lenders only distribute through intermediaries. A broker also knows the specific quirks of each lender’s underwriting, for example which lenders are flexible on one year of self-employed accounts, which accept probation period applicants, and which offer the best treatment of bonus or commission income.
Once a broker has your full picture, they run a search across the whole market and present the products you genuinely qualify for, ranked by total cost, not just headline rate. Many brokers, including the advisers we work with, offer this service fee-free, paid via lender commission rather than a fee charged to you.
Want to know what rate you’d actually qualify for?
Skip the headline rates and get a personalised comparison from over 90 lenders. Free advice, no obligation.
Broker vs Comparison Site: Side by Side
| Factor | Comparison Site | Mortgage Broker |
|---|---|---|
| Rate shown | Headline advertised rate, not personalised | Rate you are actually likely to qualify for, based on your circumstances |
| Lender access | Limited to partner lenders only | 90+ lenders including specialist, broker-only lenders |
| Complex circumstances | Not assessed; you find out at application stage | Assessed upfront, matched to the right lender first time |
| Application handling | You apply yourself once you pick a deal | Broker packages and submits the application, chases the lender |
| Credit searches | Each application to a different lender can leave a hard search | Broker uses soft searches to check eligibility before a formal application |
| Cost | Free to browse, funded by lender commission | Often free (lender-paid commission), some charge 0.3-1% of the loan |
| FCA regulation | Comparison platforms themselves are not mortgage advisers | Must be FCA-authorised to give regulated mortgage advice |
Where Comparison Sites Genuinely Help
Comparison sites are not without value. They are a reasonable first step for getting oriented in the market before you speak to anyone. If you want a rough sense of where two-year fixed rates currently sit at 75% LTV, or how a five-year fix compares to a two-year fix in general terms, a comparison table gives you that context quickly and without commitment.
They are also useful for spotting the general shape of the market, whether rates are trending up or down, which lender types (banks vs building societies) are currently most competitive, and what fee structures look like across the market. This background knowledge makes conversations with a broker more productive, because you arrive with a sense of what “normal” looks like.
If your situation is genuinely straightforward, employed, clean credit, standard deposit, standard property, a comparison site rate is more likely to reflect what you will actually be offered than it would for someone with a complex case.
Where Comparison Sites Fall Short
The core limitation of a comparison site is that it cannot assess affordability or eligibility, only display advertised pricing. This creates a gap between what you see and what you can actually get, and that gap grows the more complex your situation is.
Self-employed and contractor income. Comparison sites do not ask how your income is structured. A self-employed applicant with one year of accounts, or a contractor paid on a day rate, will see headline rates that assume standard PAYE income, then discover at application stage that many of those lenders will not accept their income as presented.
Deposit source. Whether your deposit is savings, a gift from family, or equity from a previous sale can affect which lenders will proceed. Comparison sites do not ask.
Credit history. A historic CCJ, default, or missed payment changes your available lender pool significantly. Comparison sites assume a clean credit file unless you specifically filter for bad credit products, and even then the results are generic rather than matched to your specific credit profile.
Property type. Non-standard construction, flats above commercial premises, or short lease properties all narrow your lender options. This is invisible on a standard comparison table.
Government schemes. Shared ownership, Joint Borrower Sole Proprietor arrangements, and other scheme-backed purchases follow different lender rules that most comparison sites are not built to reflect accurately.
For any of these situations, see our guides to self-employed mortgages, bad credit mortgages or contractor mortgages for how lenders assess each situation differently.
Have a situation a comparison site can’t assess?
Self-employed, contractor, adverse credit, or a non-standard property? Our advisers know which of 90+ lenders will actually say yes.
Do Brokers Really Access Deals Comparison Sites Don’t Show?
Yes. A meaningful number of UK lenders, particularly specialist and some building society lenders, distribute their products exclusively through mortgage intermediaries and do not offer them directly to consumers or list them on comparison platforms. This is a genuine structural difference, not marketing spin.
Specialist lenders like Kensington, Aldermore, Precise Mortgages and Pepper Money operate on a broker-only distribution model. If you are relying solely on a comparison site, you will never see these products, regardless of how well they might suit your circumstances. This matters most for buyers with complex income, adverse credit, or unusual property types, precisely the buyers who benefit most from a wider lender panel.
Even among mainstream lenders, some offer broker-exclusive rate tiers that are marginally better than their direct-to-consumer pricing, because they view broker-introduced business as lower risk (the application has already been packaged and checked before submission).
Specific broker-exclusive rates and lender panels change regularly. The examples above illustrate the general pattern, not a guarantee of current product availability. Always confirm current options with your adviser.
How to Use Both Together
The most effective approach is not choosing one over the other but using them in sequence. Start with a comparison site to build a general sense of the market, then move to a broker for a personalised, actionable recommendation.
Step 1: Browse a comparison site for context. Get a feel for current rate ranges by LTV band and mortgage type. This costs nothing and takes a few minutes.
Step 2: Speak to a whole-of-market broker. Bring what you learned to the conversation. A broker will assess your actual circumstances and tell you what you genuinely qualify for, including products the comparison site never showed you.
Step 3: Compare the broker’s recommendation against what you saw online. If the broker’s figure is similar to the comparison site headline rate, that is a sign your case is straightforward. If it is different, that difference is exactly the value a broker adds, either by finding you a better deal or by steering you away from a lender likely to decline your application.
Step 4: Ask your broker to confirm total cost, not just rate. Product fees, valuation costs and early repayment charges all affect the real cost of a mortgage. A good broker will present total cost over the fixed period, not just the headline percentage.
How UK Mortgage Finder Can Help
UK Mortgage Finder connects you with FCA-regulated, whole-of-market mortgage advisers who compare deals from over 90 lenders, including specialist lenders that never appear on consumer comparison sites. Our advisers take the time to understand your full circumstances before recommending anything, so the rate you see is the rate you are actually likely to get.
The service is free, with no obligation. Whether you have already browsed comparison sites and want a second opinion, or you are starting from scratch, our advisers will find the lender that best fits your situation and guide you from Agreement in Principle through to completion.
Ready for a personalised mortgage comparison?
Skip the guesswork. Get matched to lenders you actually qualify for, free and with no obligation.
Frequently Asked Questions
Is it better to use a mortgage broker or a comparison site?
For most buyers, a broker is better because they assess your full circumstances and access lenders not available on comparison sites. Comparison sites are useful for initial research but cannot confirm which rate you will actually be offered.
Are mortgage comparison sites accurate?
They accurately display advertised headline rates from partner lenders, but the rate shown is not personalised to your circumstances. The rate you actually qualify for depends on factors like income type, credit history and deposit source, which comparison sites do not assess.
Do mortgage comparison sites show every lender?
No. Comparison sites only display lenders they have a commercial partnership with. Specialist lenders that distribute exclusively through mortgage brokers, such as Kensington, Aldermore and Precise Mortgages, do not appear on consumer comparison platforms at all.
Does using a mortgage broker cost more than using a comparison site?
Not necessarily. Many brokers offer a fee-free service, paid via lender commission rather than a direct charge to you. Both routes can be free to use, though some brokers charge a fee of 0.3% to 1% of the mortgage amount, which they must disclose upfront.
Can I use a comparison site and a broker at the same time?
Yes, and this is often the most effective approach. Use a comparison site to get a general sense of the market, then speak to a broker for a personalised recommendation based on your actual circumstances.
Will using a comparison site affect my credit score?
Browsing rates on a comparison site typically does not affect your credit score, as it usually involves no credit check at the browsing stage. However, once you apply to a specific lender, that application may involve a credit search, whether you found the lender via a comparison site or a broker.
Why did a lender offer me a worse rate than the comparison site showed?
This usually happens because the advertised rate assumed a standard applicant profile that does not match your actual circumstances, for example a different LTV, income type, or credit history than what the headline rate was based on. A broker can identify this mismatch before you apply, avoiding a wasted credit search.
Are comparison sites regulated by the FCA?
Comparison sites themselves typically operate as introducers rather than regulated mortgage advisers, and usually direct you to a partner broker for actual advice. A mortgage broker giving you regulated advice must be authorised by the Financial Conduct Authority, which you can verify on the FCA Register.
Is a broker better if I am self-employed or have bad credit?
Yes, significantly. Comparison sites are built around standard applicant profiles and do not effectively account for self-employed income structures, adverse credit history, or other complex circumstances. A broker who understands specialist lender criteria can match you to a lender likely to say yes, saving time and protecting your credit file from unnecessary hard searches.
You might be interested in
How to Choose a Mortgage Lender in the UK ›
A deeper look at what to compare beyond the headline rate, and which lenders suit different circumstances.
Work out your monthly repayments and see how different rates affect your total cost.
See why comparison sites often underrepresent self-employed lending options.
Further reading
Written by Jack Taylor
UK Mortgage and Finance Expert, breaking down mortgage options and helping UK homebuyers and landlords with clear, practical guidance.
Important: Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home.
The information in this article is for guidance purposes only and does not constitute financial advice. You should seek independent advice from an FCA-regulated mortgage adviser before making any financial decisions.
HiTeck Education Ltd, trading as UK Mortgage Finder, is an Appointed Representative of Britto Brokers Ltd, which is directly authorised and regulated by the Financial Conduct Authority (FCA reference 940081).