Last updated: 26 August 2026
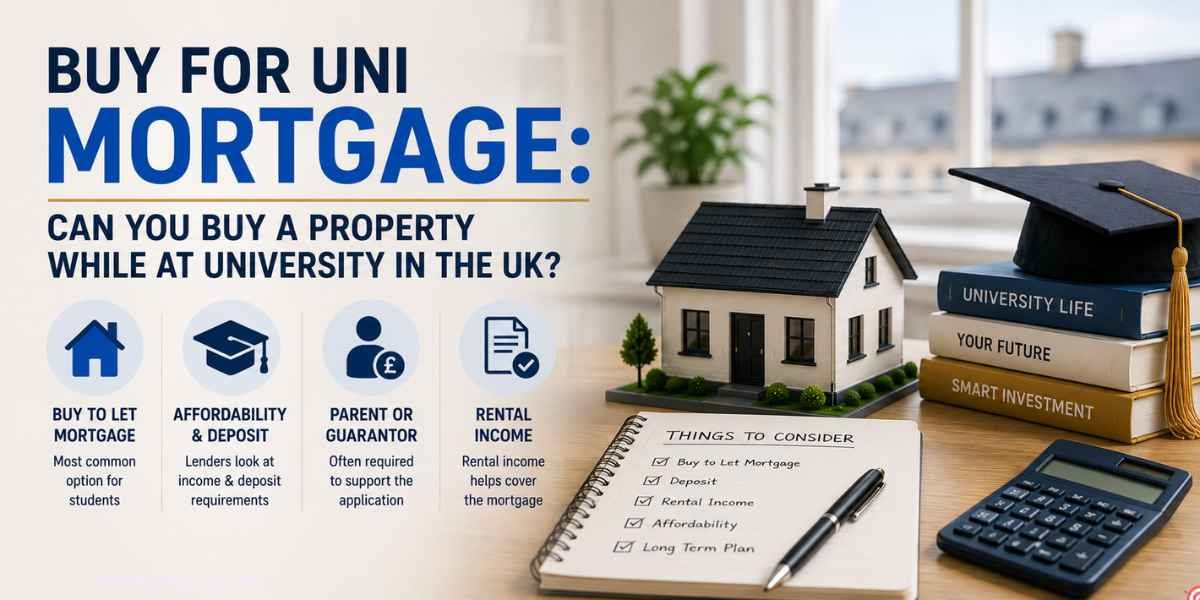
Yes. A small number of UK building societies offer a dedicated “Buy for Uni” mortgage that lets a student purchase a property near their university, live in it, and rent spare rooms to other students to cover the repayments. Bath Building Society, Vernon Building Society and Loughborough Building Society all offer these products. You can borrow up to 100% of the property value, meaning no cash deposit is required, though your parents or guardians must support the application as joint borrowers and provide security if borrowing above 80% LTV.
A Buy for Uni mortgage works on a Joint Borrower Sole Proprietor (JBSP) basis. The student is the sole legal owner of the property, but the parents join the mortgage as co-borrowers. This means the parents help with affordability (their income is assessed alongside expected rental income from spare rooms), but the property belongs to the student alone. This avoids the 3% stamp duty surcharge that applies to second homes, because the parents are not named on the title deeds.
This guide covers exactly how Buy for Uni mortgages work, which lenders offer them, what you need to qualify, and what happens after you graduate.
Ask an FCA-regulated adviser about Buy for Uni mortgages →
What’s on this page
- How does a Buy for Uni mortgage work? ⇊
- Which lenders offer Buy for Uni mortgages? ⇊
- Who is eligible? ⇊
- Do you need a deposit? ⇊
- How does rental income from housemates work? ⇊
- Does my student loan affect the mortgage? ⇊
- What happens when I finish university? ⇊
- What are the risks? ⇊
- How UK Mortgage Finder can help ⇊
- Frequently asked questions ⇊
How Does a Buy for Uni Mortgage Work?
A Buy for Uni mortgage lets a student buy a property near their university, live in it throughout their course, and rent the spare bedrooms to fellow students or other tenants. The rental income from those rooms helps cover the monthly mortgage payments, and in some cases covers them entirely. The student owns the property outright, while parents act as joint borrowers on the mortgage to satisfy the lender’s affordability requirements.
The structure is called Joint Borrower Sole Proprietor (JBSP). Here is how the roles work:
The student is the sole proprietor (owner) of the property. Their name goes on the title deeds at the Land Registry. They live in the property and manage the lettings to housemates.
The parents or guardians are joint borrowers on the mortgage. Their income is used in the affordability assessment alongside the expected rental income. They do not own the property and are not named on the deeds, which means they avoid the stamp duty surcharge on additional properties.
Most Buy for Uni products are available on either an interest-only or repayment basis. Interest-only keeps monthly payments lower during the study period, which makes the arrangement more affordable while the student is not earning a full-time salary. On a typical £200,000 property at around 6% interest, monthly interest-only payments would be roughly £1,000, which two or three rooms rented at £400 to £500 per month could partially or fully cover.
At the end of the student’s course, the property can be sold, remortgaged onto a standard residential or buy-to-let product, or the student can continue living in it and switch to a conventional mortgage once they are in full-time employment.
Which Lenders Offer Buy for Uni Mortgages?
Buy for Uni is a niche product offered by a small number of UK building societies. High street banks like HSBC, Barclays and NatWest do not currently offer dedicated student mortgage products. The three main lenders are Bath Building Society, Vernon Building Society and Loughborough Building Society. Each has slightly different criteria, rates and deposit requirements.
| Lender | Max LTV | Max Loan | Repayment Type | Key Criteria |
|---|---|---|---|---|
| Bath Building Society | Up to 100% | £500,000 | Interest-only or repayment | JBSP basis. No cash deposit required (conditions apply). Collateral charge on parental home needed above 80% LTV. Student and parents must have 3 years UK address history and permanent right to reside. Property must have good transport links to university. |
| Vernon Building Society | Up to 100% | Varies | Interest-only or repayment | JBSP basis. Student aged 18 to 30, full-time higher education in England or Wales, at least 1 year remaining on course. Max 4 bedrooms. Property within approx. 10 miles of university. Parents provide security via savings or charge on their home above 80% LTV. |
| Loughborough Building Society | Up to 80% (100% with security) | Varies | Interest-only or repayment | JBSP basis. 20% deposit required as cash in a savings account with the Society or as a collateral charge on parental property. Discounted rate from SVR for the mortgage term. England and Wales only. At least 1 full academic year remaining. |
Lending criteria and product rates correct as at August 2026 and subject to change without notice. Always confirm current criteria with your adviser before applying.
Because only a handful of lenders offer this product, speaking to a whole-of-market broker who understands student mortgages is essential. A broker can compare the three products side by side and identify which one gives the best terms for your specific situation.
Thinking about buying near your university?
Our FCA-regulated advisers can compare Buy for Uni products from multiple lenders and guide you through the application. Free advice, no obligation.
Who Is Eligible?
Buy for Uni mortgages have specific eligibility criteria that differ from standard residential mortgages. You need to meet conditions as a student, and your parents need to meet conditions as supporting borrowers.
Student requirements:
You must be aged 18 to 30 (some lenders may accept slightly older mature students on a case-by-case basis). You must be enrolled in full-time higher education at a UK university or college, with at least one full academic year remaining on your course. Part-time students are not typically eligible. International students on a student visa are not eligible. You must have permanent right to reside in the UK.
Parental requirements:
At least one parent, step-parent or grandparent must act as a joint borrower on the mortgage. They must have a stable income sufficient to support the mortgage affordability calculation alongside expected rental income. They must have at least 3 years of UK address history (Bath BS requirement). If borrowing above 80% LTV, they must provide additional security, either as a collateral charge on their own residential property or as cash held in a savings account with the building society.
Property requirements:
The property must be located near the student’s university, typically within 10 miles (Vernon BS requirement). It must be a standard residential property, usually with no more than 3 to 4 bedrooms. HMO (House in Multiple Occupation) licensing rules may apply if you rent to 3 or more unrelated tenants, depending on the local authority. Your broker or solicitor can advise on this.
Do You Need a Deposit?
Not necessarily. Bath Building Society and Vernon Building Society both offer Buy for Uni mortgages at up to 100% LTV, meaning no cash deposit from the student is required. However, when borrowing above 80% of the property value, the lender will require additional security from the parents. This usually takes one of two forms.
Collateral charge on the parental home. The lender places a second charge on your parents’ residential property, typically equivalent to 20% of the purchase price of the student property. This means your parents’ home is at risk if mortgage payments are not maintained. This is the most common route for families who do not have large cash savings.
Cash savings held with the building society. Some lenders allow parents to deposit cash (typically 20% of the purchase price) into a savings account with the society. The money earns interest but is locked as security for the duration of the mortgage. Once the mortgage is repaid or remortgaged, the savings are released.
Loughborough Building Society takes a different approach, requiring a 20% deposit upfront (either as cash or a collateral charge). Their product does not offer 100% LTV lending.
The decision between providing a collateral charge or cash savings depends on your family’s financial situation. A broker can explain the implications of each option and help you choose the right one.
How Does Rental Income from Housemates Work?
The expected rental income from letting spare rooms to other students is a core part of the Buy for Uni affordability calculation. Lenders factor this income alongside parental income when assessing whether the mortgage is affordable. In many cases, the rental income alone covers most or all of the monthly mortgage payment.
For example, if you buy a 3-bedroom property and live in one room, you can let the other two rooms at market rate. In a typical university town, student rooms rent for £400 to £600 per month each (depending on location). Two rooms at £450 per month would generate £900, which could cover the majority of an interest-only mortgage payment on a property up to around £180,000 at current rates.
You do not need an Assured Shorthold Tenancy (AST) agreement for lodgers living in your own home. Because you are the owner-occupier and your tenants share your living space, they are lodgers rather than tenants, which gives you more flexibility. However, you should still have a written lodger agreement in place for clarity. If the property has 3 or more tenants from different households, your local authority may require an HMO licence.
You can also benefit from the Rent a Room scheme, which allows you to earn up to £7,500 per year tax-free from letting furnished rooms in your own home. This is a significant advantage over a standard buy-to-let arrangement where all rental income is taxable.
Does My Student Loan Affect the Mortgage?
Student loans do not appear on your credit file in the UK, so they will not affect your credit score or show up when a lender runs a credit check. However, lenders are aware that most students have student loan obligations, and some will factor the future repayments into their affordability calculations.
For Buy for Uni products specifically, the primary affordability assessment is based on parental income and expected rental income rather than the student’s own earnings. Since most full-time students have limited or no employment income, the student loan question is less relevant than it would be for a standard residential mortgage.
Once you graduate and start earning above the repayment threshold (currently £25,000 for Plan 2 loans), your student loan repayments will be deducted from your salary at 9% of earnings above the threshold. If you remortgage to a standard product after graduation, the lender at that point will factor the student loan repayment into their affordability assessment as a committed monthly outgoing.
Want to compare Buy for Uni mortgage options?
Our advisers compare products from Bath BS, Vernon BS, Loughborough BS and other niche lenders. Free, no obligation.
What Happens When I Finish University?
This is one of the most important questions to consider before committing to a Buy for Uni mortgage. You need a clear plan for what happens to the property after graduation, because the Buy for Uni product is designed for students and will not continue indefinitely.
Option 1: Sell the property. You sell, repay the mortgage, and keep any profit (minus fees and capital gains tax if applicable). If property values have risen during your course, you could walk away from university with equity rather than just a degree. However, property values can also fall, and you would need to cover any shortfall.
Option 2: Remortgage to a standard residential mortgage. If you plan to continue living in the property after graduation, you can remortgage onto a conventional residential product once you are in full-time employment with a provable income. Your parents can be removed from the mortgage at this point.
Option 3: Remortgage to a buy-to-let mortgage. If you move away after graduation but want to keep the property as an investment, you can remortgage onto a buy-to-let product and let all the rooms to tenants. This requires a minimum 25% equity in the property and the rental income must meet the lender’s stress test (typically 125% to 145% of the mortgage payment at a higher stress rate). See our buy-to-let mortgage guide for more detail.
Most lenders expect you to have an exit strategy in place before they approve the mortgage. Your broker can help you plan for all three scenarios.
What Are the Risks?
A Buy for Uni mortgage can be a smart financial move, but it carries real risks that you and your family need to understand before committing.
Parental property at risk. If your parents provide a collateral charge on their home and mortgage payments are not maintained, the lender can pursue the parental property. This is the most serious risk and must be discussed openly within the family before proceeding.
Void periods. If you cannot find housemates for one or more rooms during parts of the year (particularly over summer), the rental income drops and the mortgage still needs to be paid. You need a plan for covering payments during void periods.
Property values can fall. If you buy at the top of the market and property values decline during your course, you could end up in negative equity when you try to sell or remortgage. This is a particular risk with 100% LTV products where you have no deposit buffer.
Maintenance and management responsibilities. As the property owner, you are responsible for repairs, maintenance, and managing housemates. Boiler breakdowns, plumbing issues and tenant disputes all fall on you. This is a real responsibility alongside your studies.
Higher interest rates. Buy for Uni products typically carry higher interest rates than standard residential mortgages, often between 6% and 8%. This is because the lender views the arrangement as higher risk due to the student’s limited income and the reliance on rental income.
Limited lender choice. With only three main lenders offering these products, you have very limited ability to shop around for competitive rates. This is another reason a broker is essential, as they can negotiate the best available terms on your behalf.
How UK Mortgage Finder Can Help
UK Mortgage Finder connects you with FCA-regulated, whole-of-market mortgage advisers who understand Buy for Uni products and can compare the options from Bath Building Society, Vernon Building Society, Loughborough Building Society and other niche lenders. Our advisers will explain the JBSP structure, help your parents understand the security requirements, and guide you through the full application process.
The service is free, with no obligation. Whether you are about to start university and want to explore buying instead of renting, or your parents are looking at this as a way to get you onto the property ladder early, our advisers can help you make an informed decision.
Exploring a Buy for Uni mortgage for your son or daughter?
Our advisers will talk you through the options, the security requirements, and what happens after graduation. Takes 2 minutes to enquire.
Frequently Asked Questions
Can a student get a mortgage in the UK?
Yes, through a Buy for Uni mortgage offered by building societies like Bath BS, Vernon BS and Loughborough BS. The student must be in full-time higher education with at least one year remaining, and a parent or guardian must act as a joint borrower on the mortgage.
Do I need a deposit for a Buy for Uni mortgage?
Not always. Bath BS and Vernon BS offer up to 100% LTV, meaning no cash deposit is required. However, above 80% LTV, parents must provide additional security either as a charge on their own home or cash savings held with the building society. Loughborough BS requires a 20% deposit.
What is a Joint Borrower Sole Proprietor mortgage?
A JBSP mortgage means the student is the sole owner of the property (their name is on the deeds), but the parents are joint borrowers on the mortgage (their income is used for affordability). This avoids the stamp duty surcharge on additional properties because the parents do not own the property.
Can I rent rooms to other students to cover the mortgage?
Yes, this is a core feature of Buy for Uni mortgages. Lenders include the expected rental income from spare rooms in their affordability calculation. The Rent a Room scheme allows you to earn up to £7,500 per year tax-free from letting furnished rooms in your own home.
Does my student loan affect my mortgage application?
Student loans do not appear on your credit file and will not affect your credit score. For Buy for Uni products, affordability is primarily based on parental income and rental income rather than the student’s earnings. After graduation, student loan repayments will be factored in if you remortgage to a standard product.
How close to my university does the property need to be?
Vernon BS requires the property to be within approximately 10 miles of your university. Bath BS requires good transport links to the university. The property should be in a location where there is genuine demand for student room rentals to support the affordability model.
What happens to the mortgage when I graduate?
You have three main options: sell the property and repay the mortgage, remortgage to a standard residential product once you are in full-time employment, or remortgage to a buy-to-let product and keep the property as an investment. Most lenders expect you to have an exit plan before they approve the mortgage.
Can international students get a Buy for Uni mortgage?
No. Buy for Uni mortgages require the student and parents to have permanent right to reside in the UK and typically at least 3 years of UK address history. International students on a student visa are not eligible for these products.
Is my parents’ home at risk?
If your parents provide a collateral charge on their own property as security for borrowing above 80% LTV, then yes, their home is at risk if mortgage payments are not maintained. Both the student’s purchased property and the parental property could be repossessed. This risk must be carefully discussed within the family before proceeding.
Do I need a mortgage broker for a Buy for Uni mortgage?
Strongly recommended. Only a small number of lenders offer these products, and the criteria, security requirements and exit planning can be complex. A whole-of-market broker can compare all available options and ensure the application is structured correctly from the start.
You might be interested in
Is Getting a Student Mortgage Possible in the UK? ›
A broader look at all the mortgage options available to students, including guarantor mortgages.
Thinking about keeping the property after graduation? See the criteria for switching to a buy-to-let product.
Work out monthly repayments on a Buy for Uni property and see how rental income offsets the cost.
Further reading
Written by Jack Taylor
UK Mortgage and Finance Expert, breaking down mortgage options and helping UK homebuyers and landlords with clear, practical guidance.
Important: Your home may be repossessed if you do not keep up repayments on your mortgage. If a collateral charge is placed on a parental property, that property is also at risk if repayments are not maintained. Think carefully before securing debts against your home.
The information in this article is for guidance purposes only and does not constitute financial advice. You should seek independent advice from an FCA-regulated mortgage adviser before making any financial decisions.
HiTeck Education Ltd, trading as UK Mortgage Finder, is an Appointed Representative of Britto Brokers Ltd, which is directly authorised and regulated by the Financial Conduct Authority (FCA reference 940081).