Last updated: 12 August 2026
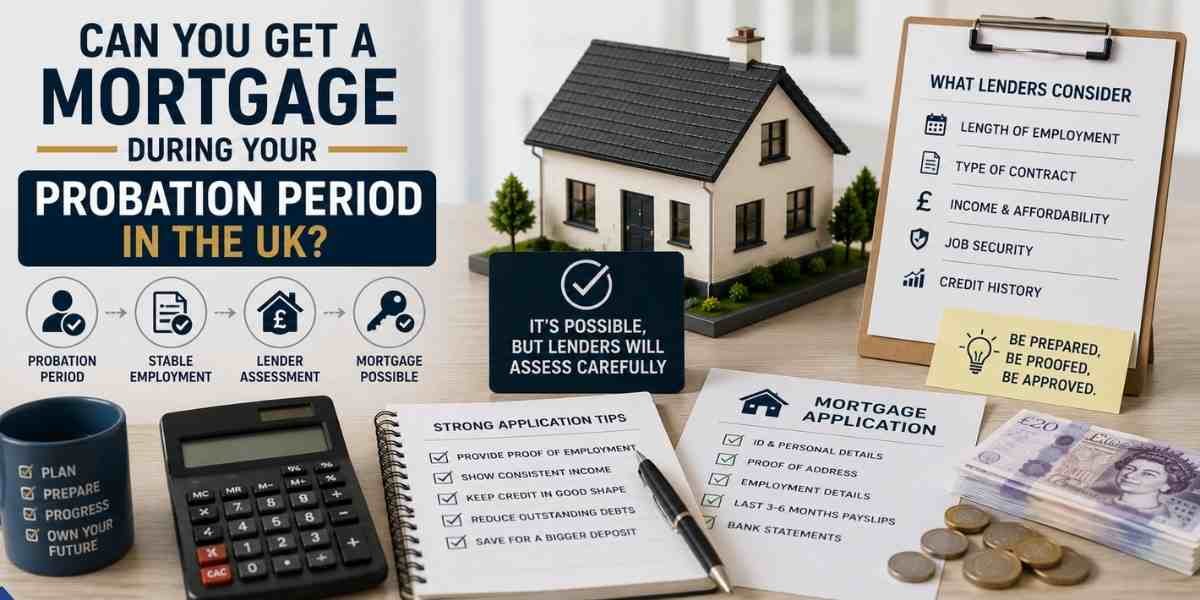
Yes, you can. Around half of UK mortgage lenders will accept an application from someone who is still in their probation period at work. Halifax, Nationwide, HSBC, Barclays, NatWest, TSB and Virgin Money all lend to probationary employees, provided you hold a signed permanent employment contract. A smaller number of lenders, including Together, Pepper Money and Precise Mortgages, will decline your application outright if probation has not been completed.
The distinction matters more than most people realise. A probation period is not the same as a temporary contract, but many buyers confuse the two and assume they cannot get a mortgage until probation ends. In most cases, that is simply not true. What lenders actually care about is whether your contract confirms permanent employment. If it does, probation is just a notice-period formality for most mainstream lenders. If it does not, your options narrow significantly.
This guide explains exactly which lenders accept probation, what your contract needs to say, how to strengthen your application, and the one critical distinction in your employment contract that most guides miss.
Speak to an FCA-regulated adviser about your probation period mortgage options →
What’s on this page
- Which UK lenders accept probation period applicants? ⇓
- The one contract detail that decides everything ⇓
- NHS, teaching and public sector probation ⇓
- What should your employer letter say? ⇓
- How to strengthen your application while on probation ⇓
- Should you wait until probation ends? ⇓
- How UK Mortgage Finder can help ⇓
- Frequently asked questions ⇓
Which UK Lenders Accept Probation Period Applicants?
Around 30 of the UK’s 60+ mortgage lenders will accept applicants who are still within their probation period, as long as the role is permanent. The rest either decline outright or add conditions that make the process harder. Here is a lender-by-lender breakdown.
| Lender | Accepts Probation? | Key Conditions |
|---|---|---|
| Halifax | Yes (with a critical condition) | Only if probation is part of a permanent contract. If the contract is purely probationary (employer decides at the end whether to offer permanent), income will NOT be used. See Section 2 below. |
| Nationwide | Yes | Signed permanent contract required. Will consider applications up to 3 months before your start date. Basic income only (overtime/bonus may be excluded). |
| HSBC | Yes | Permanent employment contract required. May consider from first payslip. |
| Barclays | Yes | Accepts probation applicants with a signed permanent contract. No additional restrictions specific to probation length. |
| NatWest | Yes | Accepts from day one of a new permanent role if you have a signed contract. An employer confirmation letter can further strengthen the case. |
| TSB | Yes | Fairly relaxed policy. May even consider future salary increases if written into the contract. |
| Santander | Yes (with time condition) | Requires 6 months total employment history, but this can be across different employers. If you moved from one permanent role to another, prior service counts. |
| Virgin Money | Yes | Permanent contract required. Must have received first payslip. Will not lend if you have been in the role for less than 6 months and have no prior employment history in the same field. |
| Skipton BS | Yes | Accepts probation period with permanent contract. Flexible on employment history. |
| Teachers BS | Yes | Specialist lender for education sector. Very comfortable with NQT probation periods. |
Lenders that typically decline probation applicants:
| Lender | Position |
|---|---|
| Together | Declines probation applicants outright. |
| Pepper Money | Declines probation applicants outright. |
| Precise Mortgages | Declines probation applicants outright. |
| Vernon BS | Will not complete until probation is finished, unless applicant has a track record in the same field. |
| Aldermore | Will not accept probation applicants in entertainment, leisure, travel or hospitality sectors. |
Lending criteria correct as at August 2026 and subject to change without notice. Always confirm current criteria with your adviser before applying.
The One Contract Detail That Decides Everything
This is the single most important thing to understand about probation period mortgages, and most guides do not explain it clearly. There are two very different types of employment contract that include a probation period, and lenders treat them completely differently.
Type 1: Permanent contract with an initial probation period. Your contract says you are employed on a permanent basis, with the first three or six months being a probation period. At the end of probation, your employment simply continues. Most mainstream lenders treat this exactly the same as permanent employment. Your income is fully accepted. This is by far the most common arrangement in the UK.
Type 2: Purely probationary contract. Your contract says you are employed on a probationary basis for three or six months, at the end of which your employer will decide whether to offer you a permanent contract. This is fundamentally different. Some lenders, including Halifax, will not use your income at all if your contract is structured this way. Your employment is conditional, not confirmed.
Halifax’s intermediary criteria page spells this out explicitly: if the probation period is part of a permanent contract, key it as “permanent” and income is used. If the contract is purely probationary with the employer having the option to terminate, key it as “probationary” and income is not used.
If you are not sure which type your contract is, read it carefully or ask your HR department. The wording matters. A broker can also review your contract and tell you immediately which type it is and which lenders will accept it.
Not sure what your contract says?
Our FCA-regulated advisers can review your employment contract and tell you exactly which lenders will accept your probation period. Free, no obligation.
NHS, Teaching and Public Sector Probation
If you work in the NHS, education, policing or the civil service, your probation period is viewed more favourably by lenders than probation in the private sector. This is because lenders understand the employment structure of these sectors and know that probation pass rates are extremely high. A newly qualified teacher on their induction year or an NHS nurse in their first 6 months is seen as very low risk.
Public sector probation periods are typically longer than private sector ones. NHS roles often have 6-month probation periods, and some civil service positions extend to 12 months. Despite the longer probation, lenders are more relaxed because the nature of the employment is stable and the contract almost always confirms permanent status from day one.
Teachers Building Society is a specialist lender that specifically caters to education professionals. If you are a newly qualified teacher (NQT) or early-career teacher (ECT), they are particularly well-suited because they understand the structure of education contracts, including the induction period that functions as probation. Other mainstream lenders like Halifax, Nationwide and NatWest also treat NHS and teaching probation favourably, especially if you can provide an employer letter confirming your role.
What Should Your Employer Letter Say?
An employer confirmation letter is not always required, but it can significantly strengthen a probation period mortgage application. Some lenders actively request one. Others treat it as supporting evidence that tips a borderline case in your favour. Either way, having one ready before you apply saves time and avoids delays.
A strong employer letter should include all of the following:
Your exact probation end date (not “approximately” or “around”). Lenders want a specific date they can verify.
A clear statement that permanent employment follows automatically from that date, without the need for a further review or decision by the employer.
Your confirmed annual salary, including any guaranteed allowances, shift supplements or London weighting.
Your notice period (both during and after probation).
Your start date and job title.
HR contact details for verification, in case the lender needs to follow up.
The letter should be dated within the last month, printed on company headed paper, and signed by an authorised person (HR manager, line manager or director). Some lenders will not accept a letter from a colleague at the same level as you.
If your employer is not sure what to write, your broker can provide a template or guidance on exactly what lenders typically expect, so the letter is right first time.
How to Strengthen Your Application While on Probation
Even with lenders that accept probation, your application is stronger if you can show the underwriter that risk is low. Probation by itself is not a problem, but probation combined with other risk factors (thin credit history, small deposit, high debt-to-income ratio) can push you into decline territory. Here is what helps:
A larger deposit. A 10% deposit opens more lender doors than 5%. If you are close to the 10% or 15% threshold, it may be worth waiting a few extra weeks to save the difference. Better LTV bands also unlock cheaper rates.
Clean credit history. No missed payments, defaults or CCJs. If your credit file has blemishes, probation on top of that narrows your lender options considerably because the specialist lenders who handle bad credit (Together, Pepper Money, Precise) are the same ones that decline probation applicants.
Continuous employment history. A gap-free work history, even across different employers, reassures lenders that your income is stable. Moving from one permanent role to another in the same industry is viewed far more positively than starting a career in a completely new field.
Professional qualifications. NHS Band grades, teaching qualifications (QTS/PGCE), or professional memberships (ACCA, CIMA, RIBA, SRA) can demonstrate career stability and make the underwriter more comfortable.
Low existing debt. Pay down credit cards and personal loans before applying. Lenders stress-test your affordability, and existing monthly commitments reduce how much they will lend you.
Should You Wait Until Probation Ends?
Not necessarily. If you have a signed permanent contract (Type 1 from Section 2), around 30 mainstream lenders will accept your application during probation. In many cases, the mortgage process itself takes 3 to 5 months from application to moving in, which means your probation may well finish before completion anyway.
However, waiting may make sense in a few specific situations:
Your contract is purely probationary (Type 2). In this case, your lender options are genuinely limited. Waiting until you receive a permanent contract will open up the full market.
You have fewer than 3 months in the role and no prior employment history. Some lenders want at least one payslip before they will assess affordability. Waiting until you have 3 months of payslips gives you the widest choice.
You have other application weaknesses. If your credit history is imperfect or your deposit is small, removing the probation element by waiting a few months can make the difference between approval and decline.
A broker can advise you on whether it is better to apply now or wait, based on your exact circumstances. Sometimes the answer is “apply now with Lender X because they do not care about probation” rather than “wait six months.”
For a broader view on job changes and mortgages, see our guide to getting a mortgage with a new job in the UK.
How UK Mortgage Finder Can Help
UK Mortgage Finder connects you with FCA-regulated, whole-of-market mortgage advisers who know exactly which lenders accept probation period applicants. Our advisers compare deals from over 90 lenders and can review your employment contract to confirm which type of probation arrangement you have (Type 1 or Type 2) before submitting to any lender.
The service is free, with no obligation. Whether you are 2 weeks into a new NHS role, 3 months into a private sector job, or about to start a position and want to know your options early, our advisers will match you to the right lender and avoid unnecessary credit searches on your file.
On probation and ready to buy?
Fill in a quick enquiry form and one of our advisers will call you back to discuss which lenders suit your situation. No fees, no pressure.
Frequently Asked Questions
Can I get a mortgage if I am still in my probation period?
Yes. Around half of UK mortgage lenders accept applicants during their probation period, provided you hold a signed permanent employment contract. Halifax, Nationwide, HSBC, Barclays, NatWest, TSB and Virgin Money all lend to probationary employees.
Does probation affect how much I can borrow?
It can, but not always. Some lenders assess your full income (basic salary, overtime, bonus) during probation. Others may only use your basic salary and exclude variable income until probation is complete. A broker can model different lender scenarios to show you the maximum borrowing available.
How many payslips do I need if I am on probation?
Most lenders require at least 1 to 3 payslips. If you have just started and only have one, lenders like Halifax, HSBC and Barclays may still consider you. Having your signed employment contract ready is essential as it replaces the payslip history that longer-serving employees would provide.
Is it harder to get a mortgage in your first week of a new job?
It is more limited but not impossible. Some lenders, including Halifax and Nationwide, accept pre-start applications up to 3 months before your start date if you have a signed permanent contract. Others need at least your first payslip. The earlier you are in your role, the fewer lenders are available, but a broker can tell you which ones are open right now.
Does it matter what industry I work in?
Yes. NHS, education, civil service and policing roles are generally viewed more favourably because lenders understand the employment structure and probation pass rates are high. Private sector roles are assessed individually. Some lenders, like Aldermore, exclude specific sectors such as entertainment, leisure, travel and hospitality from probation period lending.
Can I remortgage while on probation at a new job?
Yes. Remortgaging during probation follows the same lender criteria as a new purchase mortgage. Some lenders are actually more relaxed about remortgages because you already have a track record of mortgage repayments on the property. Nationwide, for example, will consider a remortgage during probation.
Will a probation period decline affect my credit score?
A formal mortgage application that results in a decline will leave a hard credit search on your file for 12 months. This is why it is critical to apply to the right lender first time. A broker uses soft searches to assess your eligibility before making a formal application, protecting your credit file from unnecessary hard searches.
Do I need a bigger deposit if I am on probation?
Not necessarily. The deposit requirements for probation period applicants are generally the same as for anyone else: 5% minimum for most residential mortgages. However, a larger deposit (10% or more) gives you access to more lenders, better rates, and a stronger overall application, which can help offset any concerns about probation.
Can I get a joint mortgage if only one of us is on probation?
Yes, and this can actually strengthen your application. If your partner has stable, permanent employment and a clean credit history, their income anchors the application. The lender may still assess your probationary income, but the overall case is stronger with a joint applicant in settled employment.
Should I use a mortgage broker if I am on probation?
Strongly recommended. Not all lenders treat probation the same way, and applying to the wrong one wastes a hard credit search. A whole-of-market broker knows exactly which lenders accept probation, can review your contract to confirm it meets criteria, and will present your application in the strongest possible way. This is one of the situations where a broker adds the most value.
You might be interested in
Getting a Mortgage with a New Job in the UK ›
Broader guide to how job changes affect your mortgage application, beyond just the probation element.
Working two jobs? Find out which lenders accept second job income and how much they use.
Zero-Hours Contract Mortgages UK ›
On a zero-hours contract? See which lenders still consider your application.
Further reading
Written by Jack Taylor
UK Mortgage and Finance Expert, breaking down mortgage options and helping UK homebuyers and landlords with clear, practical guidance.
Important: Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home.
The information in this article is for guidance purposes only and does not constitute financial advice. You should seek independent advice from an FCA-regulated mortgage adviser before making any financial decisions.
HiTeck Education Ltd, trading as UK Mortgage Finder, is an Appointed Representative of Britto Brokers Ltd, which is directly authorised and regulated by the Financial Conduct Authority (FCA reference 940081).