Last updated: 15 August 2026
Yes. Most UK mortgage lenders will consider overtime, bonus and commission income as part of your mortgage affordability assessment. But the percentage they accept varies enormously, from 50% to 100%, depending on the lender, how consistent the income is, and how long you have been receiving it. Choosing the wrong lender could leave tens of thousands of pounds of your earning power on the table.
If a significant portion of your total pay comes from overtime shifts, an annual performance bonus, quarterly sales commission, or any combination of these, the lender you apply to matters more than almost anything else. Two people with identical incomes can receive very different borrowing figures simply because one applied to a lender that uses 100% of their bonus and the other applied to one that caps it at 50%. This guide shows you exactly which lenders are most generous with each type of variable income, what evidence they need, and how to maximise your borrowing.
Speak to an FCA-regulated adviser about your overtime, bonus or commission income →
What’s on this page
- Do UK lenders accept overtime, bonus and commission income? ⇓
- How do lenders calculate overtime for a mortgage? ⇓
- How do lenders assess bonus income for a mortgage? ⇓
- How do lenders treat commission income? ⇓
- Which UK lenders are most generous with variable income? ⇓
- What if 100% of my income is commission? ⇓
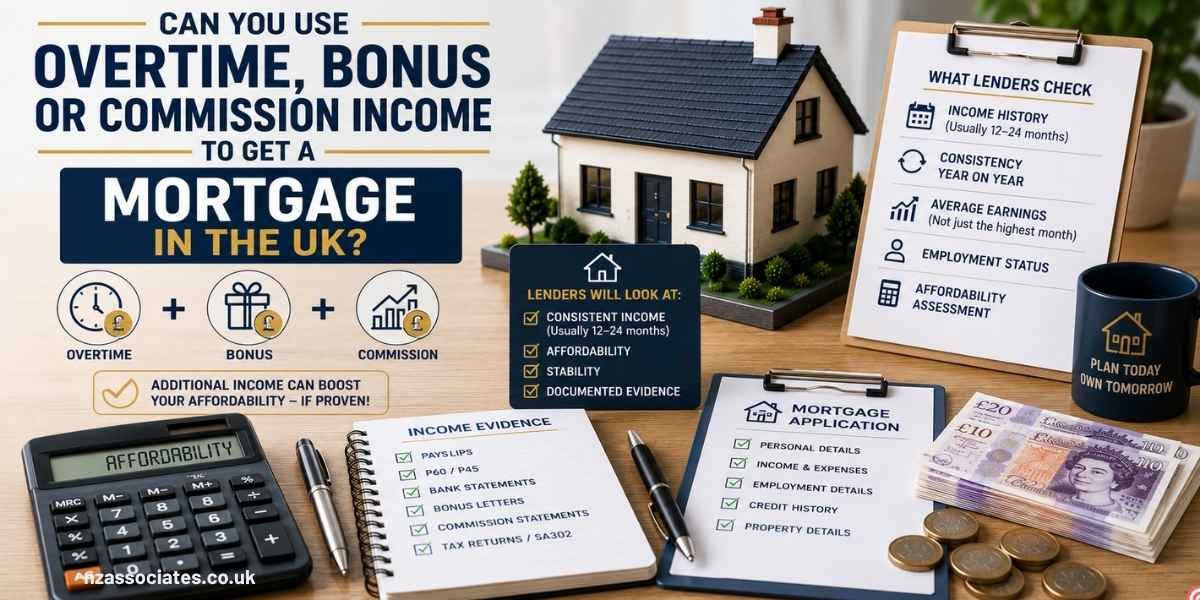
- What documents do you need to evidence variable income? ⇓
- How much more could you borrow? ⇓
- How UK Mortgage Finder can help ⇓
- Frequently asked questions ⇓
Do UK Lenders Accept Overtime, Bonus and Commission Income?
Yes, the majority of UK mortgage lenders accept some or all of your variable income. However, they do not treat it the same way they treat your basic salary. Variable income is assessed separately, averaged over a period (usually 3 to 12 months for overtime, 2 to 3 years for bonuses), and often discounted. The percentage a lender uses, typically somewhere between 50% and 100%, is one of the single biggest factors determining how much you can borrow.
Lenders classify your income into two buckets: guaranteed and variable. Your basic salary is guaranteed. Overtime, bonuses and commission sit in the variable bucket. The way they handle the variable bucket breaks down as follows:
Guaranteed overtime (written into your contract, e.g. compulsory weekend shifts) is treated almost like basic salary by many lenders. Some will use 100% of it with just 3 months of payslip evidence.
Non-guaranteed overtime (voluntary extra shifts) is treated more cautiously. Lenders average it over 6 to 12 months and typically use 50% to 100% depending on consistency.
Annual bonuses are averaged over 2 to 3 years using P60s or payslips. Most lenders use 50% of the average. Some, like Kensington, Hodge and Santander, can go up to 100%.
Commission follows a similar pattern to bonuses but can be more complex, particularly for 100% commission-based roles like estate agents, recruiters and financial advisers. Lenders want to see regularity and sustainability.
How Do Lenders Calculate Overtime for a Mortgage?
Lenders split overtime into two categories: guaranteed and non-guaranteed. Guaranteed overtime, where your contract states you must work a set number of additional hours, is viewed almost identically to basic salary by most lenders. Non-guaranteed overtime, where you choose to pick up extra shifts or hours, is averaged and discounted. The distinction is critical because it can change how much you borrow by thousands of pounds.
Guaranteed overtime: If your contract says you work a minimum of 8 hours overtime per week at a set rate, many lenders will count 100% of that income. You typically only need 3 months of payslips showing the overtime appearing consistently. This is common in healthcare (NHS band staff doing compulsory on-call), policing (overtime rotas), and manufacturing (shift premiums).
Non-guaranteed overtime: If overtime is voluntary and varies month to month, lenders will average it over 6 to 12 months and then apply a haircut, typically between 50% and 100%. The more consistent and regular the overtime, the higher the percentage they will use. If your overtime drops significantly in one month, it brings the average down and reduces your borrowing.
A practical tip: if you know you are going to apply for a mortgage in 6 months, try to maintain consistent overtime levels during that period. A steady £400 per month over 6 months is better evidence than £800 one month and £100 the next, even though the total is similar.
How Do Lenders Assess Bonus Income for a Mortgage?
Annual bonuses are one of the most misunderstood income types in UK mortgage lending. Lenders want to see a track record of receiving bonuses over 2 to 3 years, and they average those figures to calculate a sustainable number. Most mainstream lenders then use 50% of that average. A smaller group use up to 100%, which can add significantly to your borrowing power.
There are three main averaging methods lenders use, and the choice of method can shift your affordability outcome by 15% to 25% on the same evidence:
Method 1: Straight average over 2-3 years. The lender adds your last 2 or 3 annual bonuses and divides by the number of years. If you earned £8,000, £10,000 and £12,000 in bonuses over 3 years, the average is £10,000. This is the most common method.
Method 2: Latest year only. Some lenders use only the most recent year’s bonus. If your bonuses are trending upwards, this method gives the highest figure. If they are trending down, it gives the lowest.
Method 3: Lowest of the last 2-3 years. A handful of more conservative lenders use the lowest bonus figure from the review period. This is the most cautious approach and typically gives the lowest borrowing figure.
The method a lender uses is usually not negotiable. This is why choosing the right lender matters so much. A broker who understands these differences can match you to the lender whose method and percentage work best for your specific bonus profile.
Earning overtime, bonuses or commission?
Our FCA-regulated advisers know which lenders give the best treatment to variable income. Free advice, no obligation.
How Do Lenders Treat Commission Income?
Commission income is assessed similarly to bonuses but with added complexity, especially when commission forms a large proportion of your total pay. Lenders want to see that your commission is regular, sustainable and backed by at least 6 to 12 months of payslip evidence. Most use a percentage of the average, typically 50% to 100%, depending on consistency and the lender’s appetite.
The key question lenders ask about commission is: what proportion of your total income does it represent? Someone earning a £40,000 basic salary plus £5,000 annual commission is straightforward. Someone earning £20,000 basic plus £30,000 commission is a very different risk profile, because their income depends heavily on sales performance.
Lenders who are comfortable with high-commission roles include Kensington (up to 100% of regular commission), Santander (100% if regular and consistent, 70% if regular but inconsistent), and Hodge (up to 100%). More cautious lenders like Virgin Money cap variable income at 60% (or 75% with a 3-year track record).
If your commission fluctuates seasonally (common in recruitment, property sales, and automotive), make sure your broker chooses a lender that averages over a period long enough to capture your full cycle. A lender that only looks at the last 3 months could catch you in a quiet quarter and undervalue your real earning power.
Which UK Lenders Are Most Generous with Variable Income?
This is the table that can save you thousands of pounds. The percentage of variable income a lender accepts directly affects your maximum borrowing. The difference between a lender using 50% and one using 100% of a £15,000 annual bonus, at a 4.5x income multiple, is £33,750 in borrowing power.
| Lender | Overtime | Bonus | Commission | Key Notes |
|---|---|---|---|---|
| Santander | 70-100% | 70-100% | 70-100% | 100% if regular and consistent. 70% if regular but inconsistent. One of the most generous mainstream lenders for variable income. |
| Kensington | Up to 100% | Up to 100% | Up to 100% | Specialist lender, broker-only. Very generous on regular variable income. Accepts complex income structures. |
| Hodge | Up to 100% | Up to 100% | Up to 100% | Specialist lender, broker-only. Particularly strong on bonus income for professional roles. |
| Halifax | 50-100% | 50% | 50% | Uses higher % for guaranteed overtime. Averages variable income over available period. One of the largest lender panels. |
| NatWest | 50-100% | 50% | 50% | Higher percentage for longer track records. Averages over 6-12 months for overtime. |
| Accord (Yorkshire BS) | 60% | 60% | 60% | Accepts 60% of sustainable overtime and bonus, capped so total variable income does not exceed basic salary. |
| Virgin Money | 60% (up to 75%) | 60% (up to 75%) | 60% (up to 75%) | 60% standard. Up to 75% with a 3-year track record (2 years if paid monthly or more frequently). |
| Barclays | 50% | 50% | 50% | Conservative on variable income. Uses 50% of average over available period. |
| HSBC | 50% | 50% | 50% | Standard 50% treatment. May be more flexible for existing Premier customers. |
| Nationwide | 50% | 50% | 50% | Requires 6 months evidence. Reliable but not the most generous for variable income. |
Lending criteria correct as at August 2026 and subject to change without notice. Always confirm current criteria with your adviser before applying.
The pattern is clear: if variable income is a large part of your pay, Santander, Kensington and Hodge are significantly more generous than the typical 50% offered by Barclays, HSBC and Nationwide. A broker who understands these differences can add tens of thousands to your maximum borrowing.
What If 100% of My Income Is Commission?
If you work on a 100% commission basis with no basic salary, you can still get a mortgage, but your lender options narrow and the evidence requirements are stricter. This is common among estate agents, recruitment consultants, financial advisers, some insurance brokers and certain sales roles. Lenders treat you essentially as self-employed, even if you are technically PAYE.
For 100% commission roles, lenders typically require at least 12 months of payslips or P60s showing consistent earnings. Some want 2 years. They will average your commission over the review period and apply a percentage, usually between 50% and 100%. The FCA’s 2026 Mortgages Report noted that more lenders have broadened their criteria for variable income in recent years, and a growing number now accept 100% of commission with sufficient evidence.
The key to success with a 100% commission application is presenting consistency. Monthly payslips that show roughly similar amounts each month are far stronger evidence than payslips that swing wildly between £2,000 and £8,000. If your income is seasonal, make sure the averaging period is long enough to smooth out the peaks and troughs.
Lenders like Kensington and Hodge are particularly strong for 100% commission earners because they have manual underwriters who assess the case individually rather than running it through an automated affordability engine that might reject non-standard income patterns.
What Documents Do You Need to Evidence Variable Income?
The documents you need depend on the type of variable income and the lender’s specific requirements. Having everything ready before you apply avoids delays and back-and-forth with the underwriter. Here is a checklist for each income type.
For overtime:
Latest 3 to 6 months of payslips showing overtime clearly itemised as a separate line. Your employment contract or a letter from your employer confirming whether overtime is guaranteed or voluntary. Bank statements showing the net pay arriving each month.
For annual bonuses:
P60s for the latest 2 to 3 years (these confirm your total annual earnings including bonuses). Recent payslips showing the bonus payment if it falls within the current tax year. A letter from your employer confirming the bonus structure (is it discretionary, contractual, performance-based?) and historical bonus figures. Some lenders also accept a screenshot from your employer’s HR portal if it shows bonus history.
For commission:
Latest 3 to 12 months of payslips showing commission payments. P60s for the latest 1 to 2 years. A letter from your employer confirming the commission structure (base + commission split, whether commission is uncapped, typical earning range). If you are paid 100% commission, you may also need your SA302 tax calculations from HMRC if the lender treats you as self-employed.
For all variable income types:
Photo ID, proof of address, proof of deposit source, and 3 months of bank statements. Your broker will tell you exactly what your chosen lender requires before you submit, so nothing is missing.
How Much More Could You Borrow?
The difference between a lender that uses 50% of your variable income and one that uses 100% is not trivial. Here is a worked example showing the impact on a real-world borrowing scenario.
| Scenario | Income Used | Max Borrowing (4.5x) | Difference |
|---|---|---|---|
| Basic salary only | £35,000 | £157,500 | Baseline |
| + £10,000 bonus (50% used) | £35,000 + £5,000 = £40,000 | £180,000 | +£22,500 |
| + £10,000 bonus (100% used) | £35,000 + £10,000 = £45,000 | £202,500 | +£45,000 |
| + £10,000 bonus + £6,000 overtime (100% used) | £35,000 + £10,000 + £6,000 = £51,000 | £229,500 | +£72,000 |
That is an extra £72,000 in borrowing power by choosing a lender that uses 100% of both your bonus and overtime, compared to one that only considers your basic salary. In many parts of the UK, that is the difference between a two-bed flat and a three-bed family home.
To model your own figures, try our mortgage calculators.
Want to see how much your variable income is really worth?
Our advisers will model your overtime, bonus and commission across multiple lenders to find the one that gives you the highest borrowing. Free, no obligation.
How UK Mortgage Finder Can Help
UK Mortgage Finder connects you with FCA-regulated, whole-of-market mortgage advisers who understand how different lenders treat overtime, bonus and commission income. Our advisers compare deals from over 90 lenders and know exactly which ones use 100% of your variable income, which averaging method each one applies, and how to present your income evidence in the strongest way.
The service is free, with no obligation. Whether you are an NHS nurse earning regular overtime, a sales manager with a large annual bonus, a recruitment consultant on 100% commission, or any combination of these, our advisers will find the lender that maximises your borrowing power.
Frequently Asked Questions
Can overtime count towards a mortgage in the UK?
Yes. Most UK lenders accept overtime income. Guaranteed overtime (written into your contract) is typically accepted at up to 100%. Non-guaranteed overtime is averaged over 6 to 12 months and used at between 50% and 100% depending on the lender and how consistent it is.
Do bonuses count for mortgages in the UK?
Yes. Most lenders average your bonus over 2 to 3 years and use between 50% and 100% of that average. Lenders like Santander, Kensington and Hodge are among the most generous, accepting up to 100% of regular bonuses. More conservative lenders like Barclays and HSBC typically use 50%.
Can I get a mortgage if all my income is commission?
Yes, but your lender options are more limited. You will typically need 12 to 24 months of consistent payslips or P60s. Specialist lenders like Kensington and Hodge are comfortable with 100% commission earners. A broker can identify which lenders accept your income structure without wasting hard credit searches.
How many months of payslips do I need to show overtime or commission?
Most lenders want 3 to 6 months of payslips for overtime and 6 to 12 months for commission. For annual bonuses, P60s covering the last 2 to 3 years are usually required. The longer and more consistent the track record, the higher the percentage a lender will use.
Does the percentage a lender uses really make that much difference?
Yes, it can be significant. On a £10,000 annual bonus at a 4.5x income multiple, the difference between a lender using 50% and one using 100% is £22,500 in borrowing power. For higher earners with large bonuses or consistent overtime, the gap can exceed £50,000.
Will a lender accept my bonus if I have only received it once?
Some lenders will, but most prefer at least 2 years of bonus history to establish a pattern. If you have only received one bonus, a smaller number of lenders may still consider it, particularly if your employer confirms it is a regular part of the compensation structure. A broker can identify which lenders are flexible here.
Can I use overtime, bonus and commission together to boost my borrowing?
Yes. Lenders assess each type of variable income separately and add them to your basic salary. If you earn overtime, a bonus and commission, all three can count. Some lenders, like Accord (Yorkshire BS), cap total variable income at your basic salary level. Others, like Santander and Kensington, do not have this cap.
Does it matter if my bonus is discretionary rather than contractual?
Discretionary bonuses are still accepted by most lenders, but they may use a lower percentage or require a longer track record. A contractual bonus (guaranteed in your employment contract) is treated more favourably. Either way, 2 to 3 years of P60 evidence showing the bonus being paid consistently is the strongest proof.
Can variable income help with a buy-to-let mortgage?
For buy-to-let, the primary affordability test is based on rental income covering the mortgage payment, not your personal income. However, some lenders require a minimum personal income (typically £25,000) to qualify. Your overtime, bonus and commission can count towards meeting that threshold. See our buy-to-let mortgage guide for more.
Should I use a broker if my income includes overtime, bonus or commission?
Strongly recommended. The variation between lenders on variable income is one of the biggest in UK mortgage lending. A lender that uses 100% of your bonus could lend you £45,000 more than one that uses 50%. A whole-of-market broker knows which lenders are most generous and which averaging method works best for your income pattern.
You might be interested in
Working two jobs? Find out which lenders accept second job income and how much they use.
How lenders assess day-rate and fixed-term contract income for mortgage affordability.
Work out your monthly repayments and see how adding variable income changes what you can afford.
Further reading
Written by Jack Taylor
UK Mortgage and Finance Expert, breaking down mortgage options and helping UK homebuyers and landlords with clear, practical guidance.
Important: Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home.
The information in this article is for guidance purposes only and does not constitute financial advice. You should seek independent advice from an FCA-regulated mortgage adviser before making any financial decisions.
HiTeck Education Ltd, trading as UK Mortgage Finder, is an Appointed Representative of Britto Brokers Ltd, which is directly authorised and regulated by the Financial Conduct Authority (FCA reference 940081).