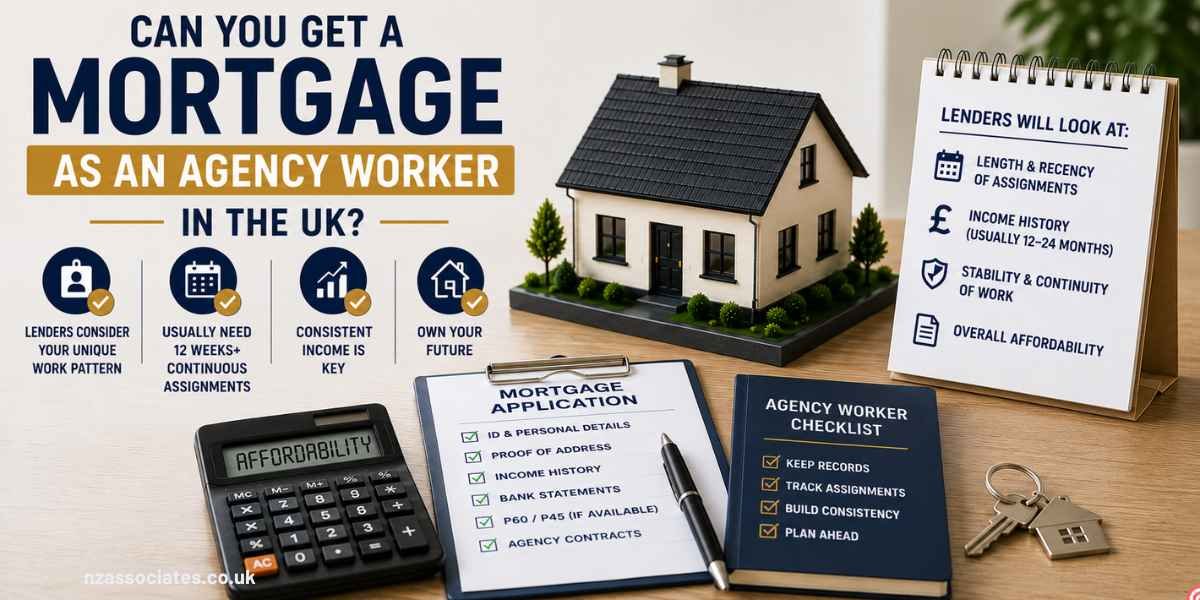
Yes, agency workers can get a mortgage in the UK, though your lender options are smaller than for permanent employees and the evidence requirements are stricter. Most lenders want to see at least 12 months of continuous agency work with gaps between assignments of no more than 6 weeks. Your income is typically averaged over the past 12 months, and lenders apply an income multiple of 4 to 4.5 times that average to determine your maximum borrowing.
Around 1 million people in the UK work through recruitment agencies, according to the Recruitment and Employment Confederation (REC). From NHS agency nurses and care workers to warehouse operatives, office temps and industrial staff, agency work is a major part of the UK employment landscape. Yet many agency workers assume they cannot get a mortgage because their work is not permanent. That assumption is outdated. The Agency Workers Regulations 2010 gave temporary workers stronger legal protections, and lenders have responded by creating clearer criteria for assessing agency income.
This guide explains exactly which lenders accept agency workers, how they calculate your income, what documents you need, and how different types of agency work are treated.
Speak to an FCA-regulated adviser about your agency worker mortgage options →
What’s on this page
- Which UK lenders accept agency workers? ⇊
- How do lenders calculate agency worker income? ⇊
- Agency worker vs contractor: what is the difference for mortgages? ⇊
- How different sectors are treated ⇊
- What about gaps between assignments? ⇊
- What documents do you need? ⇊
- How to strengthen your application ⇊
- How UK Mortgage Finder can help ⇊
- Frequently asked questions ⇊
Which UK Lenders Accept Agency Workers?
Not all lenders accept agency worker income, but a good number of mainstream and specialist lenders do, provided you can demonstrate a consistent track record. The minimum history most lenders want to see is 12 months of continuous agency work, though a small number will consider you from 6 months.
| Lender | Accepts Agency Workers? | Minimum History | Key Notes |
|---|---|---|---|
| Halifax | Yes | 12 months | Uses 12-month average of agency income. Requires payslips and bank statements showing consistent earnings. Gaps between assignments should not exceed 6 weeks. |
| Nationwide | Yes | 12 months | Requires continuous agency work in the same line of work for 12 months. Will use the average of 12 months of payslips. |
| NatWest | Yes | 12 months | Accepts agency income averaged over 12 months. Current contract or active placement must be in place at point of application. |
| Kensington | Yes | 6 months | Specialist lender, broker-only. One of the most flexible for agency workers. Can use contract rate to annualise income. Accepts from 6 months with consistent work history. |
| Precise Mortgages | Yes | 12 months | Specialist lender, broker-only. Comfortable with agency workers in most sectors. Higher deposit may be required (15%+). |
| Aldermore | Yes | 12 months | Specialist lender, broker-only. Accepts agency workers with 12 months history. May exclude entertainment, leisure and hospitality sectors. |
| Skipton BS | Yes | 12 months | Flexible building society. Requires evidence of consistent agency work in the same sector. |
| Barclays | Case by case | 12 months preferred | No blanket policy. Underwriter discretion. Stronger cases more likely to be approved. |
Lending criteria correct as at August 2026 and subject to change without notice. Always confirm current criteria with your adviser before applying.
The pattern is clear: 12 months of continuous agency work opens the majority of lenders. Kensington stands out for accepting agency workers from just 6 months, and their willingness to annualise a contract rate rather than simply averaging payslips can give a higher borrowing figure.
How Do Lenders Calculate Agency Worker Income?
Lenders use one of two methods to calculate your income as an agency worker. The method they choose directly affects how much you can borrow, so understanding the difference matters.
Method 1: 12-month average. This is the most common approach. The lender takes your total gross earnings from your last 12 months of payslips, divides by 12 to get a monthly figure, and multiplies by 12 to get your annualised income. If your earnings varied across the year, the average smooths everything out. Most high street lenders use this method.
Method 2: Contract rate annualisation. Some lenders, particularly specialist ones like Kensington, will take your current hourly or daily rate, multiply it by your contracted hours per week, and annualise it over 46 to 48 weeks (allowing for holidays). This method can produce a significantly higher income figure than a 12-month average, especially if you have recently moved to a better-paying assignment.
For example, if you earn £14 per hour through your agency, work 40 hours per week, and the lender annualises over 46 weeks:
£14 x 40 hours x 46 weeks = £25,760 annualised income
If your actual earnings over the last 12 months were lower because you had a 2-month gap between placements, a lender using the 12-month average might calculate your income as £20,000 or less. The difference at 4.5x income is over £25,000 in borrowing power.
A broker can identify which method each lender uses and steer you towards the one that gives the best result for your specific earnings pattern.
Working through an agency and want to know your mortgage options?
Our FCA-regulated advisers know which lenders accept agency income and how to maximise your borrowing. Free advice, no obligation.
Agency Worker vs Contractor: What Is the Difference for Mortgages?
Agency workers and contractors are often grouped together, but lenders treat them differently. Understanding which category you fall into affects which products are available and how your income is assessed.
Agency worker: you are employed by a recruitment agency (Hays, Reed, Adecco, etc.) and placed with a client company. The agency pays your wages, deducts tax and NI through PAYE, and handles your employment admin. You receive payslips from the agency. Examples: agency nurses, warehouse temps, office admin, teaching supply staff.
Contractor: you work independently, usually through your own limited company or via an umbrella company. You negotiate your own day rate directly with the client. You manage your own tax. Examples: IT contractors, engineering consultants, interim managers.
The key difference for mortgage purposes is that agency workers are PAYE employees of the agency and provide payslips as evidence, while contractors are typically self-employed or paid through a limited company and provide contracts, accounts and SA302s.
If you are a contractor rather than an agency worker, our contractor mortgages guide covers the specific lender criteria for day-rate and fixed-term contract work.
How Different Sectors Are Treated
Not all agency work is viewed equally by mortgage lenders. The sector you work in affects how the underwriter perceives the stability of your income and the likelihood of continued placements.
Healthcare (NHS agency nurses, care workers, HCAs). This is one of the strongest sectors for agency worker mortgages. The NHS and care sector have a structural shortage of staff, meaning agency nurses and care workers rarely experience long gaps between assignments. Lenders understand this and are generally comfortable lending. Teachers Building Society (which also covers healthcare professionals) has specialist criteria that suit this profile.
Industrial and warehouse (logistics, manufacturing, food processing). Agency work in warehousing and logistics is very common. Lenders accept this income provided you can show 12 months of consistent work. Seasonal peaks (Christmas, Black Friday) can actually boost your average if you work more hours during those periods.
Office and admin (reception, data entry, PA, finance temps). Generally well-accepted. Office temp work through agencies like Office Angels, Hays or Robert Half is viewed as stable provided you have a consistent track record.
Education (supply teachers, teaching assistants). Supply teaching through agencies is common and well-understood by lenders. However, income drops during school holidays (July and August) can bring down your 12-month average. Teachers Building Society is particularly sympathetic to this pattern.
Construction and trades. Accepted by most lenders with 12 months history, though the cyclical nature of construction means lenders may scrutinise gaps more carefully. CSCS card holding and consistent placements with the same agency help.
Entertainment, hospitality and leisure. This is the hardest sector. Some lenders, including Aldermore, specifically exclude agency workers in these industries. Your options are narrower, but not zero. Kensington and some building societies may still consider you.
What About Gaps Between Assignments?
Gaps between agency placements are the single biggest concern lenders have with agency worker applications. Most lenders will accept short gaps of up to 6 weeks between assignments without issue. Longer gaps raise questions about the sustainability of your income.
If you have had a gap of more than 6 weeks in the last 12 months, some lenders will still consider you, but they may use a lower income figure, require a larger deposit, or ask for a written explanation. If the gap was for a clear reason (holiday, illness, caring responsibility, a planned break between long placements), a brief explanation from you or your agency can resolve the concern.
The best way to protect your mortgage application is to minimise gaps. If you know you are planning to buy a property in the next 6 to 12 months, keep your placements as continuous as possible. Even short assignments between longer placements help, because they keep your work history unbroken on paper.
What Documents Do You Need?
Agency worker mortgage applications require more evidence than a standard employed application. Having everything ready before you apply avoids delays.
From your agency: latest 12 months of payslips, your current assignment details or contract showing your role, rate and expected duration, and a reference letter from the agency confirming your employment start date, continuity of work, and current assignment.
From you: P60 for the most recent complete tax year, latest 3 months of bank statements showing your agency pay arriving, photo ID, proof of address, and proof of deposit source.
If you work with multiple agencies: provide payslips and reference letters from each one. Lenders will combine the income but need to see the full picture.
Agency reference letter. A strong letter should confirm: your start date with the agency, total continuous employment period, current assignment details (client, role, hourly/daily rate, expected end date or ongoing status), and confirmation that your work is PAYE. Some lenders specifically ask for this.
How to Strengthen Your Application
Agency worker applications benefit from preparation. The stronger your evidence of income stability, the more lenders will be available and the better rates you can access.
Build 12 months of unbroken work history. This is the single most important step. At 12 months continuous, the majority of agency-friendly lenders open up.
Keep gaps under 6 weeks. Even a short assignment between longer placements keeps your record continuous.
Stay in the same sector. Moving between healthcare and warehouse work in the same 12-month period looks unstable. Staying in one sector demonstrates transferable, in-demand skills.
Save a larger deposit. A 10% deposit gives you access to more lenders and better rates than 5%. At 15%, specialist lenders like Kensington and Precise open up with more competitive products.
Clean your credit file. Pay down credit cards, clear any small defaults if possible, and make sure you are on the electoral roll.
Use a broker. Not all lenders advertise their agency worker criteria publicly. A broker knows which lenders genuinely follow through on accepting agency income.
For additional income that could boost your borrowing, see our guides to overtime, bonus and commission mortgages and second job mortgages.
Agency worker ready to buy?
Our advisers compare over 90 lenders and know exactly which ones accept agency income. Free, no obligation, no wasted credit searches.
How UK Mortgage Finder Can Help
UK Mortgage Finder connects you with FCA-regulated, whole-of-market mortgage advisers who understand how lenders treat agency worker income. Our advisers compare deals from over 90 lenders, know which ones use the 12-month average method versus contract rate annualisation, and can identify the lender that gives your income the best treatment.
The service is free, with no obligation. Whether you are an NHS agency nurse, a warehouse operative, a supply teacher, or an office temp, our advisers will match you to the right lender and handle the paperwork from Agreement in Principle through to completion.
Not sure which lender will accept your agency income?
Fill in a quick form and our advisers will call you back with your options. Takes 2 minutes.
Frequently Asked Questions
Can agency workers get a mortgage in the UK?
Yes. A number of mainstream and specialist lenders accept agency worker income, typically requiring at least 12 months of continuous agency work. Some specialist lenders like Kensington may accept from 6 months. A whole-of-market broker can identify which lenders suit your situation.
How much can an agency worker borrow for a mortgage?
Most lenders apply a multiple of 4 to 4.5 times your annual income, calculated either as a 12-month average of your actual earnings or by annualising your current hourly or daily rate. The method used can significantly affect the figure, so choosing the right lender matters.
How long do I need to have been an agency worker to get a mortgage?
Most lenders require 12 months of continuous agency work. A small number of specialist lenders will consider you from 6 months. The work should be in the same sector, with gaps between assignments of no more than 6 weeks.
Do gaps between agency placements affect my mortgage application?
Short gaps of up to 6 weeks are generally acceptable. Longer gaps may reduce your lender options or require explanation. Keeping your work history as continuous as possible in the 12 months before applying gives you the widest choice of lenders.
Is an agency worker the same as a contractor for mortgage purposes?
No. Agency workers are employed by the agency and paid through PAYE with payslips. Contractors are typically self-employed or work through their own limited company. Lenders have different criteria and income assessment methods for each. If you are a contractor, see our contractor mortgages guide.
Does the sector I work in matter?
Yes. Healthcare, industrial, office and education agency workers are generally well-accepted. Entertainment, hospitality and leisure agency work is harder because some lenders specifically exclude these sectors.
Can an agency nurse get a mortgage?
Yes, and healthcare is one of the strongest sectors for agency worker mortgages. The NHS and care sector have persistent staff shortages, meaning agency nurses rarely face long gaps between placements. Most mainstream lenders are comfortable with agency nursing income once you have 12 months of consistent work.
Do I need a bigger deposit as an agency worker?
Not necessarily, but a larger deposit helps. Most lenders accept agency worker applications from 5% deposit, but having 10% or 15% opens up more lenders and unlocks better interest rates.
What if I work through multiple agencies at the same time?
This is fine. Lenders can combine income from multiple agencies. You will need to provide payslips and reference letters from each one. Working with multiple agencies can actually strengthen your case by showing that you are in demand.
Should I use a mortgage broker as an agency worker?
Strongly recommended. Not all lenders advertise their agency worker criteria clearly, and some that appear to accept agency income will decline at underwriting. A broker who specialises in non-standard income knows which lenders genuinely accept agency workers and avoids wasted hard credit searches.
Last updated: 21 August 2026
You might be interested in
How day-rate and fixed-term contract income is assessed, and which lenders use contract rate annualisation.
Zero-Hours Contract Mortgages UK ›
On a zero-hours contract through your agency? See which lenders still accept your application.
Overtime, Bonus & Commission Mortgages ›
Earning overtime or shift premiums through your agency? See which lenders give the best treatment.
Further reading
Written by Jack Taylor
UK Mortgage and Finance Expert, breaking down mortgage options and helping UK homebuyers and landlords with clear, practical guidance.
Important: Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home.
The information in this article is for guidance purposes only and does not constitute financial advice. You should seek independent advice from an FCA-regulated mortgage adviser before making any financial decisions.
HiTeck Education Ltd, trading as UK Mortgage Finder, is an Appointed Representative of Britto Brokers Ltd, which is directly authorised and regulated by the Financial Conduct Authority (FCA reference 940081).