Last updated: 6 September 2026
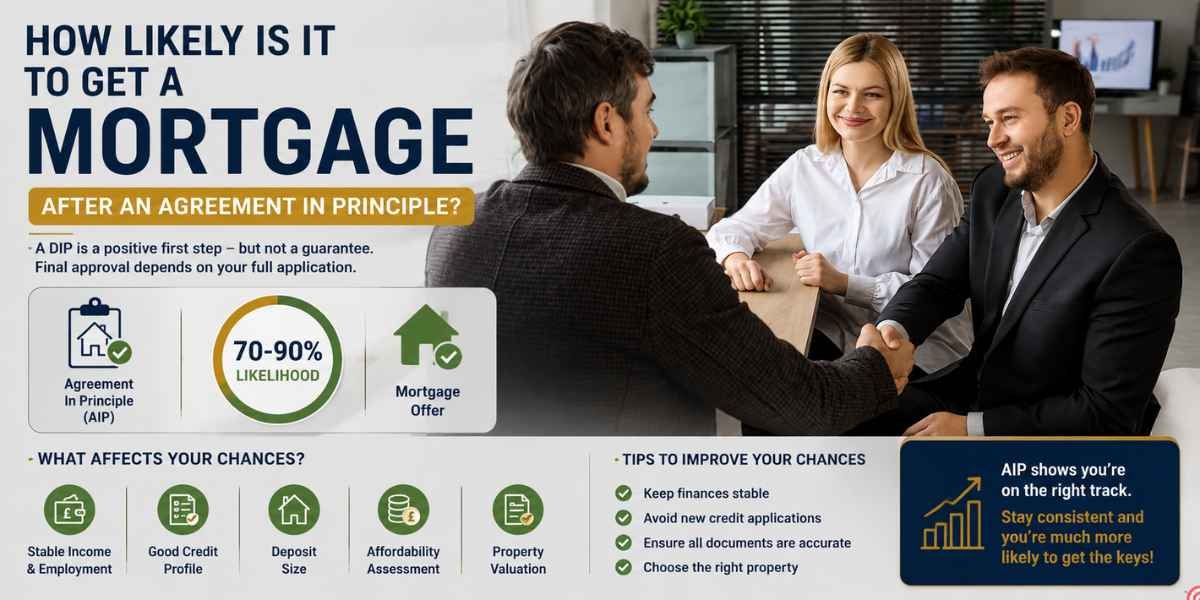
Very likely. Around 90% to 95% of mortgage Agreements in Principle (AIPs) go on to convert into a full mortgage offer. The remaining 5% to 10% are declined during the formal application stage, usually because something has changed in the borrower’s circumstances, the property valuation raises concerns, or information provided at the AIP stage turns out to be inaccurate. An AIP is a strong signal that a lender is willing to lend to you, but it is not a guarantee.
Understanding the gap between an AIP and a full mortgage offer is important because it affects how you behave after receiving your AIP. Taking on new debt, changing jobs, missing a payment, or choosing a property the lender considers risky can all turn a positive AIP into a decline at the final hurdle. This guide explains exactly what an AIP is, what happens between AIP and full offer, the most common reasons for decline, and how to protect your application at every stage.
Speak to an FCA-regulated mortgage adviser about your AIP and next steps →
What’s on this page
- What is an Agreement in Principle? ⇊
- How likely is approval after AIP? ⇊
- What happens between AIP and full mortgage offer? ⇊
- 7 reasons a mortgage can be declined after AIP ⇊
- How to protect your application after getting an AIP ⇊
- Does an Agreement in Principle affect your credit score? ⇊
- Declined after AIP? What to do next ⇊
- How UK Mortgage Finder can help ⇊
- Frequently asked questions ⇊
What Is an Agreement in Principle?
An Agreement in Principle (also called a Decision in Principle, Mortgage in Principle, or Mortgage Promise) is a statement from a lender confirming they would, in principle, lend you a certain amount based on a preliminary review of your finances. It is not a formal mortgage offer. It is a conditional indication that the lender is likely to say yes, subject to a full application, detailed affordability checks, credit verification and a satisfactory property valuation.
An AIP typically takes 15 to 60 minutes to obtain, either online or through a broker. You provide basic information about your income, outgoings, employment and the amount you want to borrow. The lender runs an initial affordability check and, in most cases, a soft credit search (which does not leave a visible footprint on your credit file for other lenders to see).
Most AIPs are valid for 60 to 90 days, depending on the lender. After that, you may need to renew if you have not yet found a property or submitted a full application. Renewing is usually straightforward as long as your circumstances have not changed.
An AIP serves two practical purposes. First, it tells you roughly how much you can borrow, which helps you set a realistic budget when house hunting. Second, estate agents and sellers take your offer more seriously if you can show an AIP, because it demonstrates that a lender has already assessed your finances at a preliminary level.
How Likely Is Approval After AIP?
Around 90% to 95% of AIPs convert to a full mortgage offer. This means that if you have received an AIP, the odds are strongly in your favour. The 5% to 10% who are declined after AIP almost always fall into one of a small number of identifiable categories, and in most cases the decline could have been avoided with better preparation or advice.
The reason the conversion rate is so high is that the AIP already filters out the most common barriers. Your income has been checked against the lender’s affordability model, your credit file has been reviewed at a basic level, and the requested loan amount has been assessed against the lender’s maximum lending criteria. What remains after AIP is verification (proving the information you provided is accurate) and property-specific assessment (confirming the property is suitable security for the loan).
If your AIP was arranged through a whole-of-market broker who conducted a detailed fact-find before placing the application, your conversion rate is likely even higher than the market average. Brokers pre-screen your application against the lender’s full criteria before submitting, which catches most of the issues that would otherwise cause a decline at the formal stage.
Got an AIP and want to make sure the full offer goes through?
Our FCA-regulated advisers check your application against the lender’s full criteria before submission. Free advice, no obligation.
What Happens Between AIP and Full Mortgage Offer?
Once you have found a property and had an offer accepted, the process moves from AIP to full mortgage application. This is where the lender verifies everything and assesses the property itself. Several things happen during this stage.
Full affordability assessment. The lender conducts a detailed review of your income, outgoings and committed debts. They stress-test your ability to repay at a higher interest rate (typically the lender’s SVR or a rate significantly above your product rate) to ensure you can still afford the payments if rates rise.
Hard credit check. While the AIP may have used a soft search, the full application usually involves a hard credit search. This is a more thorough review of your credit history and will be visible to other lenders for 12 months. Any issues that did not appear in the soft search, or any changes to your credit file since the AIP, will be picked up here.
Document verification. You submit proof of income (payslips, P60s, SA302s for self-employed), proof of deposit, ID, and proof of address. The lender checks these against what you declared at AIP stage. Any discrepancy, even an innocent one, can trigger additional questions or a decline.
Property valuation. The lender instructs a surveyor to value the property. This confirms the property is worth what you are paying for it and is suitable security for the mortgage. If the valuation comes back lower than the purchase price (a “down-valuation”), you may need to find a larger deposit, renegotiate the price, or walk away.
Underwriter review. A human underwriter (or in some cases, an automated system) reviews the complete package: your finances, your credit file, and the property valuation. This is the final decision point. If everything checks out, you receive a formal mortgage offer.
The typical timeline from full application to formal offer is 2 to 6 weeks, depending on the lender and the complexity of your case. Conveyancing (legal work) runs in parallel and typically takes another 8 to 12 weeks before completion.
7 Reasons a Mortgage Can Be Declined After AIP
If a mortgage is declined after AIP, there is always a specific reason. Understanding these reasons helps you avoid them. Here are the seven most common.
1. Change in financial circumstances. Taking on new debt (a car finance deal, a credit card, a buy-now-pay-later agreement), changing jobs, moving to a lower salary, or losing overtime or bonus income between your AIP and full application. The lender reassesses your affordability at the full application stage, and if your numbers have changed, the outcome can change too.
2. Inaccurate information at AIP stage. If the income, deposit or debt figures you provided at AIP turn out to be different when verified with documents, the lender may decline. This is not necessarily dishonesty. Rounding up your salary, forgetting about a small personal loan, or underestimating your credit card balances can all cause a mismatch.
3. Credit file issues discovered at hard search. The hard credit check at full application stage is more thorough than the soft search used for the AIP. Missed payments, defaults, CCJs or excessive recent credit applications that did not appear in the soft search can now surface. Even small issues, like a missed mobile phone payment, can affect your application with some lenders.
4. Property valuation problems. A down-valuation (where the surveyor values the property below the agreed purchase price) changes your LTV ratio. If your deposit no longer covers the gap, the lender may decline or offer a smaller loan. Non-standard construction (concrete prefab, steel frame, thatched roof), structural issues, or a property above a commercial premises can also trigger a valuation decline.
5. Lender criteria changes. Lenders can update their lending criteria at any time, and occasionally the rules that applied when your AIP was issued have changed by the time you submit a full application. This is rare but does happen, particularly during periods of economic uncertainty or regulatory change.
6. Debt-to-income ratio too high. High street lenders typically cap your debt-to-income ratio at 40% to 45% of gross annual income. If your total committed debts (projected mortgage payment, credit cards, loans, car finance, student loan repayments) push above this threshold, the lender will decline. This is one of the most common reasons for post-AIP decline and one of the most avoidable.
7. Deposit source issues. Lenders need to verify where your deposit comes from (anti-money-laundering regulations require this). If your deposit is gifted, borrowed, or from an overseas source, additional checks apply. If you cannot provide a clear paper trail for your deposit, the lender may decline or delay the application.
How to Protect Your Application After Getting an AIP
The period between receiving your AIP and submitting your full application is critical. What you do (or do not do) during this window directly affects whether your mortgage converts to a full offer. Here are the rules to follow.
Do not take on any new credit. No car finance, no new credit cards, no buy-now-pay-later, no personal loans. Every new credit agreement changes your debt-to-income ratio and leaves a hard search on your credit file. Even a small agreement can tip you over a lender’s threshold.
Do not change jobs. If possible, stay in your current role until after your mortgage completes. Changing jobs during the application resets your employment status. If you must change, tell your broker immediately so they can assess whether the new role still meets the lender’s criteria. See our new job mortgage guide for how lenders treat job changes.
Do not miss any payments. Keep every financial commitment current, including credit cards, utilities, mobile phone contracts, council tax and rent. A single missed payment during the application window can cause a decline.
Do not make large unexplained deposits into your bank account. Lenders review your bank statements for the last 3 months. Large, unexplained cash deposits trigger anti-money-laundering checks. If someone is gifting you money for the deposit, keep a clear paper trail (bank transfer from named donor, signed gift letter).
Do keep your credit card balances low. Stay below 30% of your available credit limit. High credit utilisation can lower your credit score between AIP and full application.
Do respond quickly to lender requests. When the lender or your broker asks for a document, provide it the same day if possible. Delays in supplying evidence can cause your application to time out or fall behind other cases in the lender’s queue.
Need help navigating from AIP to full offer?
Our advisers manage the full application process, chase the lender, and flag potential issues before they become declines. Free, no obligation.
Does an Agreement in Principle Affect Your Credit Score?
In most cases, no. The majority of UK lenders now use a soft credit search for AIPs, which does not appear on your credit file and is invisible to other lenders. This means you can obtain multiple AIPs from different lenders without damaging your credit score, which is useful if you are comparing options through a broker.
However, a small number of lenders still use a hard credit search for AIPs. A hard search is visible to other lenders for 12 months and can slightly lower your credit score, particularly if you have multiple hard searches in a short period. Before applying for an AIP, check with your broker or lender whether they use a soft or hard search.
The full mortgage application that follows the AIP will almost always involve a hard credit search. This is unavoidable and is a normal part of the process. One hard search from a mortgage application has minimal impact on your credit score and is understood by other lenders as a routine step in the home-buying process.
Declined After AIP? What to Do Next
A decline after AIP is stressful, but it is not the end of the road. Different lenders have different criteria, and a decline from one does not mean every lender will say the same thing. Here is a practical step-by-step approach.
Step 1: Find out exactly why you were declined. The lender is obliged to tell you the reason. Common reasons include affordability, credit issues, property valuation, or a change in circumstances. You need the specific reason before you can fix anything.
Step 2: Do not rush into another application. Every full mortgage application leaves a hard credit search on your file. Multiple applications in quick succession can make your credit profile look desperate to other lenders. Take time to understand and address the issue first.
Step 3: Check your credit file. Order your full credit report from all three UK agencies (Experian, Equifax, TransUnion). Look for errors, missed payments, defaults, or unexpected entries. Dispute anything incorrect.
Step 4: Speak to a whole-of-market broker. A broker can review why you were declined, identify which lender is more likely to approve your application given the specific issue, and submit a stronger application the second time round. This is especially important if the decline was related to income type, employment status, or property type, where different lenders have genuinely different criteria.
For more on mortgage declines and complex situations, see our guides to bad credit mortgages, self-employed mortgages and probation period mortgages.
How UK Mortgage Finder Can Help
UK Mortgage Finder connects you with FCA-regulated, whole-of-market mortgage advisers who manage the full process from AIP through to completion. Our advisers pre-screen your application against the lender’s detailed criteria before submission, which catches potential problems early and maximises your chances of converting your AIP into a full offer.
The service is free, with no obligation. Whether you are about to apply for your first AIP, have an AIP and want to make sure the full application goes smoothly, or have been declined after AIP and need expert guidance on what to do next, our advisers can help.
Ready to get your Agreement in Principle, or need help after a decline?
Fill in a quick enquiry form and one of our advisers will call you back. Takes 2 minutes, no fees, no pressure.
Frequently Asked Questions
How likely am I to get a mortgage after an Agreement in Principle?
Around 90% to 95% of AIPs convert to a full mortgage offer. The 5% to 10% that are declined usually involve a change in the borrower’s circumstances, inaccurate information at AIP stage, or a property valuation issue. Using a broker who pre-screens your application increases your chances further.
Is an Agreement in Principle the same as a mortgage offer?
No. An AIP is a preliminary indication that a lender is likely to lend you a certain amount. A formal mortgage offer comes after the full application, including detailed affordability checks, a hard credit search, document verification and property valuation. The AIP is the starting point, not the finish line.
Can a mortgage be declined after AIP?
Yes. An AIP is not a guarantee. The most common reasons for post-AIP decline are changes in your financial circumstances, credit file issues discovered at hard search stage, property valuation problems, or inaccurate information provided at AIP stage.
Does an AIP affect my credit score?
Most lenders use a soft credit search for AIPs, which does not affect your credit score or appear on your file. A small number use a hard search. Always check with your broker or lender before applying. The full mortgage application that follows will involve a hard search.
How long does an Agreement in Principle last?
Most AIPs are valid for 60 to 90 days, depending on the lender. After that, you can usually renew as long as your circumstances have not changed significantly.
Can I get multiple AIPs from different lenders?
Yes, provided the lenders use soft credit searches (which most do). Multiple soft searches do not affect your credit score. Your broker can obtain AIPs from several lenders to compare options without any impact on your credit file.
What should I avoid doing after getting an AIP?
Do not take on new credit (car finance, credit cards, buy-now-pay-later), change jobs, miss any payments, or make large unexplained deposits into your bank account. All of these can change your affordability assessment or raise red flags during the full application.
What happens if the property is down-valued?
If the surveyor values the property below the agreed purchase price, your LTV ratio increases. You may need to find a larger deposit, renegotiate the purchase price with the seller, or in some cases, walk away and find a different property. Your broker can advise on the best course of action.
Can I apply to another lender if I am declined after AIP?
Yes, but take time to understand why you were declined first. Applying to another lender with the same issue will likely result in the same outcome and add another hard search to your credit file. A broker can identify which lender is more likely to approve you given the specific reason for your decline.
Do I need an AIP before making an offer on a property?
It is not legally required, but most estate agents will ask for one before accepting your offer. An AIP shows the seller you are a serious buyer with the financial backing to complete the purchase. In competitive markets, not having an AIP can put you at a disadvantage against other buyers who do.
You might be interested in
How to Choose a Mortgage Lender in the UK ›
Compare brokers, banks and comparison sites to find the right lender before you apply.
Work out your monthly repayments and see how much you could afford before getting your AIP.
Declined after AIP due to credit issues? Find out which specialist lenders still consider your application.
Further reading
Written by Jack Taylor
UK Mortgage and Finance Expert, breaking down mortgage options and helping UK homebuyers and landlords with clear, practical guidance.
Important: Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home.
The information in this article is for guidance purposes only and does not constitute financial advice. You should seek independent advice from an FCA-regulated mortgage adviser before making any financial decisions.
HiTeck Education Ltd, trading as UK Mortgage Finder, is an Appointed Representative of Britto Brokers Ltd, which is directly authorised and regulated by the Financial Conduct Authority (FCA reference 940081).